Banks: utilities, cartel or both?
Photo by Floriane Vita on Unsplash
Banks are becoming instruments, rather than conduits, of monetary policy.
In the developed world in particular, since the 2008 financial crisis, banks have been subjected to some brutal regulatory changes. From pricing caps on loans, to floors on deposits, to rising capital buffer requirements under Basel 3 – the list goes on, and the pain for many minority shareholders is seemingly endless.
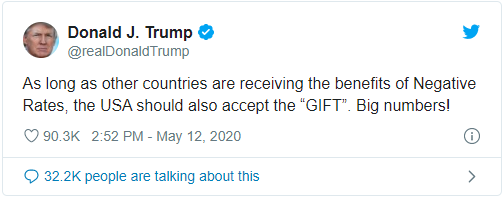
Some would say it is well deserved. Certain countries (led by the emerging world) have gone one step further in terms of their involvement in the banking sector, with the government either fuelling the dominance of state-owned banks over private players. And then there's those that take outright stakes in formerly “private” banks (in both friendly and less than amicable manners), in order to exercise an increasingly populist form of monetarism: offering the supposed “GIFT” of zero/negative interest rates.
One would expect that the reaction of banks and their shareholders to such regulation and state-sanctioned intervention would be to lobby against the passing of these changes, as they are so seemingly detrimental to their bottom lines.
Yet we struggled to find evidence of meaningful pushback from any senior banking chief. In fact, we have the likes of JP Morgan Chief Jamie Dimon, whose tenure in the Chief Executive seat actually predates the financial crisis, making comments like this:
“I believe there were people … who were greedy, selfish, did the wrong stuff, overpaid themselves and couldn’t give a damn. Yes.”
One would be forgiven for starting to think that when it comes to regulation, banks are – to some extent – asking for it. Maybe they are.
Prima Facie.
What we observe is an industry that’s struggling to regain its pre-crisis glory under the burden of increased regulation, including the need to hold increased capital buffers for use when the rainy day comes. Of course, rainy days are declared not by the weather but by the banks themselves, and until they do, those buffers are to remain untouched – even if protecting these buffers actually causes a “rainy day”, declared or otherwise.
Interpreting the numbers is a case of glass half full/empty. For example, take this data from the European Banking Federation looking at the average return on equity of EEA banks:
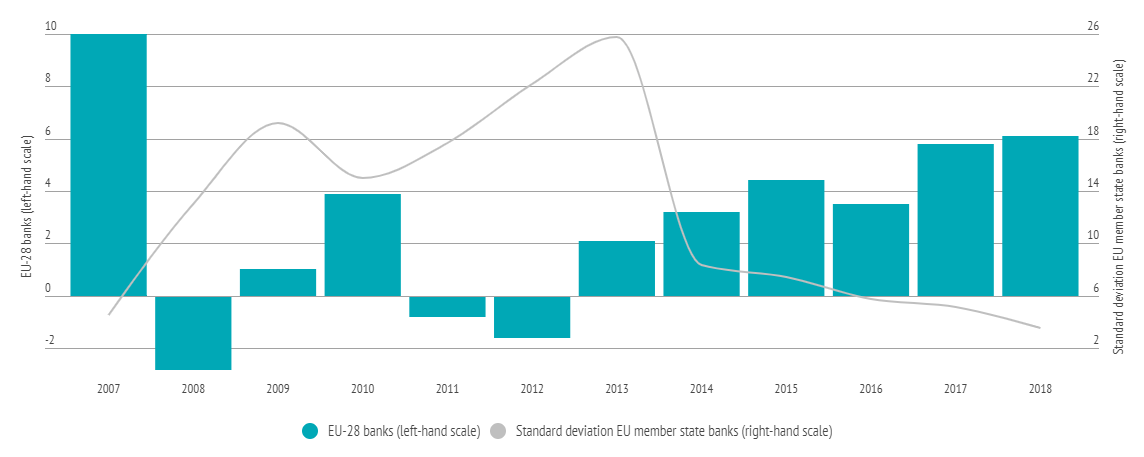
The green bars (Return on Equity, LHS scale) tell the story we already know: that banks have staged a recovery. But return levels are about 30-40% below their pre-crisis levels, even after more than a decade of support. What is interesting is the slightly nondescript grey line, showing the standard deviation of the ROE figures (RHS scale): there is barely any left.
Every EU bank is starting to look like every other EU bank. A similar picture is found in the US data, as released by the St. Louis Fed:
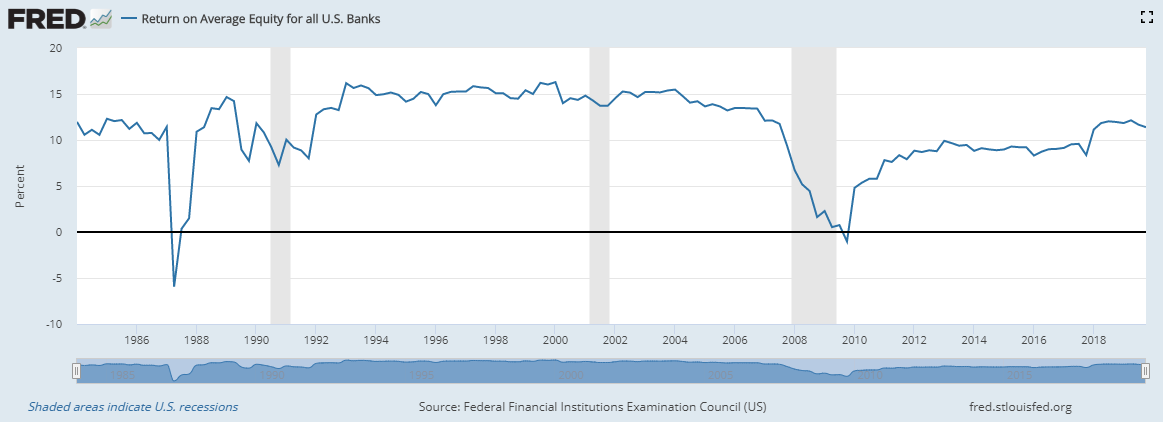
The absolute levels of ROE are higher, thanks to US rates not having been pushed to near-zero (yet), but the trajectories are similar; c. 30% below the pre-crisis averages. While the St. Louis Fed doesn’t provide a standard deviation of these ROE numbers across the sample population, a quick look at publicly available data confirms the hunch:
US banks are starting to look like one another – and they’re starting to look like EU banks.
The business of banking (as a utility).
The economics behind these observations is simple: the business of banking involves taking capital from those who are unwilling to take risk (depositors), underwriting that risk with a fixed rate of return (deposit rate) and then taking risk on that money and receiving a higher rate that compensates for that astuteness in pricing risk (lending rate).
The profit for the banker is the spread between the average lending rate and the average deposit rate, commonly known as the “Net Interest Margin” of a bank. Of course, banking profits include other forms of revenue, like fee income which are very much independent of the interest rate environment but do not scale as a percentage of a bank’s size (read “less operating leverage”), but the traditional image of the banker is one of a perpetual money-printing machine. If only the spread matters, then making money is a matter of relative cost and revenue.
Except that in reality, it isn’t. Add a sprinkle of populism into the picture, when politics and business collide, and economic theory gets thrown out the window. Nowhere is it more obvious than in Japan and increasingly the EU: while theory suggests that a spread can be maintained whether interest rates are positive or not, reality suggests that the zero lower bound does exist, especially in the eyes of a retail depositor.
For example, in Japan, savers have put up with near-zero interest for years, despite a negative interest rate policy in place since 2016; at the same time, banks have kept bank accounts free of charge for depositors. Accounts cost the banks money: think ATMs, internet banking, bank staff, call centres, payment systems etc. On the flip side, borrowers (and the central bank) expect that rate cuts are accompanied by a corresponding cut in the lending rate, the ultimate aim of easing monetary policy being to make credit available at a cheaper rate to spur growth. Banks are subsidising depositors, while seeing their revenues get squeezed: revenues down, costs flat. Not great.
The same is starting to happen in the EU, as seen in the latest financial stability report published last month by the ECB:
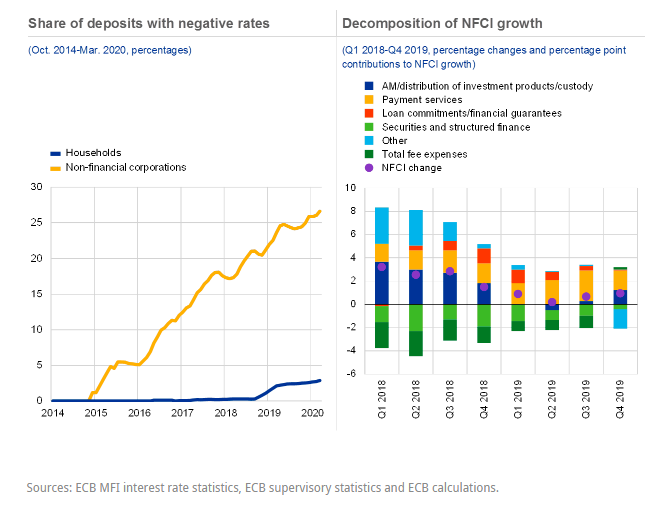
For corporates, bending over backwards to stomach a negative interest rate on a business account is at best palatable. For households, it’s a red line that many are reluctant to cross. The ECB first introduced negative interest rates in June 2014. 6 years on, less than 5% of retail deposit accounts have seen a negative deposit rate.
Instituting rate cuts is clearly turning out for central banks to be a case of “Heads I win, tails you lose”, with commercial banks taking the pain, while central bankers reap the kudos. And many other countries are catching onto the trick: from Poland to Turkey to South Africa, and potentially Southeast Asia and Latin America, the cat is out of the bag and rates are collapsing, accelerated (and vindicated in the eyes of policymakers) by the COVID-19 crisis.
Commercial banks have no choice, since depositors would more likely take their deposits out and stuff them under their bed (or into a government security) than be willing to pay a charge for a bank account that was previously free, or take the pain of a negative deposit rate. Furthermore, a coordination problem exists, for as long as one other bank is willing to pay a slightly higher deposit rate, it starts drawing deposits from its competitors.
Ultimately, it seems that the “will of the people” has provided a backstop to the political costs of negative interest rates and, in some cases, the fiscalisation of government deficits. On the flipside, banks and their shareholders foot the bill to maintain an unstable and unprofitable equilibrium.
Everyone not only needs credit now. It’s no longer optional, and in the past few months – as a result of the COVID-19 crisis – everyone believes they have a RIGHT to credit. Just like water, gas and electricity. And if everyone needs it, everyone should have it, and no one should make a big profit out of it because it is a RIGHT.
Just as it is with water, gas and electricity: turn the banks into a utility to supply much needed credit to the masses, without having to pay a single cent for it. What a brilliant piece of policy!
The cartel of non-risk.
At this point, we could start entertaining the idea that the pain that banks are feeling today could be an intermediate-stage struggle for the formation of a cartel. But a cartel of what?
Traditionally, cartels collude to raise the price of the product they’re selling, in order to put the price above the competitive price level. Today, we’re selling falling prices of debt. So what exactly do we think the banks are setting up a cartel for? Why are most banks happily sitting back and allowing regulators to slap increasingly onerous rules on them?
Our hypothesis of the bigger-picture play is as follows. And we’d love to hear opinions (especially those that disagree with us) on this.
We think that the answer lies in the unstable equilibrium described above: a solution to the coordination problem. By utilising regulation as a coordinating tool across the large incumbents, new challengers are discouraged from entering the market, reducing the risk of the collusive equilibrium being disrupted.
As we saw in the case of UK fintech banking startups Revolut and Monzo (and the plethora of others), growth has its challenges; especially so when the growth they seek is dependent on being able to use infrastructure provided by the very firms with whom they are threatening to compete.
Coordination and compliance (with the rules of the cartel) is key. But what rule are they seeking to enforce? As the saying goes, a penny saved is a penny earned: saving on costs is a much quicker way to increase profits. Whereas a traditional cartel puts prices up, this cartel seeks to put costs down.
What is the biggest obstacle to getting those spreads between lending and funding rates up? It’s not the central banks or government policy. It’s everybody else; households who resist the absolutely irrational notion of a negative yield, of paying someone to hold money. And how does one break that resistance? By making sure that there is no alternative – that no other bank cheats.
What is formed is the purchaser’s analogue of a monopoly: a monopsony on deposits that can dictate the cost of funding for the entire banking system with its suppliers (households) having little to no pricing power to push back with. A monopsony on non-risk, on “safety”.
Monopsonies usually exist in labour markets, but to form a monopsony in the market for risk is something else altogether. Put in the context of the risk drift that we are continuing to see in markets, it is easy to understand why governments could possibly condone such an outcome: by removing the zero lower bound on rates, government securities become compelling instruments again. Better near-zero yield government debt than negative deposit rates.
Now that would make a lot of sense to a big bank boss, and to any government running (or planning to run) a fiscal deficit, a true GIFT that keeps on giving.
Say hello to our new utility provider.
As with all things, we’ll only be able to tell if we’re right on this hypothesis as time goes on. It remains unclear if this is indeed the underlying hope of all involved in banking regulation; what is clear is that the banking sector is being structurally challenged, whether as a result of direct or indirect state intervention. It’s difficult to tell if governments and regulators are in on the play.
For the foreseeable future, the headwinds against banks are clear: the zero lower bound holds (at least for deposit rates), and governments would very much prefer to have minority shareholders take the pain of narrowing spreads than for depositors to suffer negative yielding savings accounts.
As it stands, it looks more likely than not that banks are being transformed into utilities. And until (or unless) something changes, they should be treated and valued as such: increasingly regulated upside, perhaps constrained downside, but certainly not the engines of infinite growth they used to be.
But unlike any other utility, when it comes to money, the line between whether one is on the demand or supply side of the equation is never clear. There’s no way anyone can force a producer of any good to supply it at a negative price forever. But the same can’t be said for a supplier of funding and deposits, unless they find an exit route from fiat money.
For the moment, the suppliers (depositors) are holding out and keeping funding costs up (albeit at near-zero), and banks – or at least their minority shareholders – are taking the pain from the gap in rates. Could this change in the future? Never say never.